Chinese Cosmetics Market Offers Huge Opportunities (2026)
Big opportunities for Chinese cosmetics market. These last years, cosmetics products are increasingly successful among Chinese consumers. In 2015, Chinese women spent 31.39 billion US dollars on cosmetics. By 2025, China’s beauty and personal care market reached over 90 billion USD, making it the second-largest cosmetics market in the world. Each household in China uses around three Chinese skin care products versus seven for Korean brands.
Chinese Brands Rising
Chinese brands are becoming huge competitors. Surveys show Chinese consumers are interested in using Chinese cosmetics products. During the in-cosmetics Asia event, over 40 Chinese ingredients were presented by providers for innovative cosmetics brands. In 2025, homegrown labels like Proya, Florasis, and Winona captured significant market share, particularly among Gen Z consumers who value ingredient transparency and cultural identity in their skincare choices.
Korean Cosmetics Still a Reference
Korean cosmetics products attract more Chinese consumers and are among favorite foreign goods in China. Korean beauty products are part of skin care routines worldwide, with usage frequencies from 10 to 30 steps depending on countries.
Essence prepares skin to receive other products called serums, which target specific concerns like wrinkles, acne, and dark spots. Herborist, a Chinese brand, offers natural products and provides guides explaining product application steps.
Skin Brightening and Anti-Aging Remain Priorities
Brightening skin to look younger is a key priority for Chinese women, rooted in historical associations between white skin and wealth. L’OCCITANE created the “Reine Blanche” product range dedicated to Chinese consumer needs. In 2025, anti-aging serums and brightening ampoules are among the fastest-growing product categories on Chinese e-commerce platforms. We worked with Novexpert to position their peptide-based serums exactly on this demand, with strong results on Xiaohongshu and Tmall.
E-Commerce Drives the Market
The e-commerce market is vital. Chinese consumers prefer purchasing cosmetics and luxury products online through platforms like Tmall Global, JD.com, and Jumei.com. L’OREAL was the first international company to sell on Tmall Global in 2010. Today, cross-border e-commerce (CBEC) through Tmall Global and JD Worldwide continues to be the primary entry point for international brands entering China without a local entity. In 2025, live commerce on Douyin drove over 30% of beauty product sales during major shopping festivals like 618 and Double 11.
Social Media: From WeChat to Xiaohongshu
Social media platforms like Weibo and WeChat are essential. Chanel promoted lipsticks on WeChat by allowing users to shake smartphones and view color changes between products, demonstrating interactive engagement approaches.
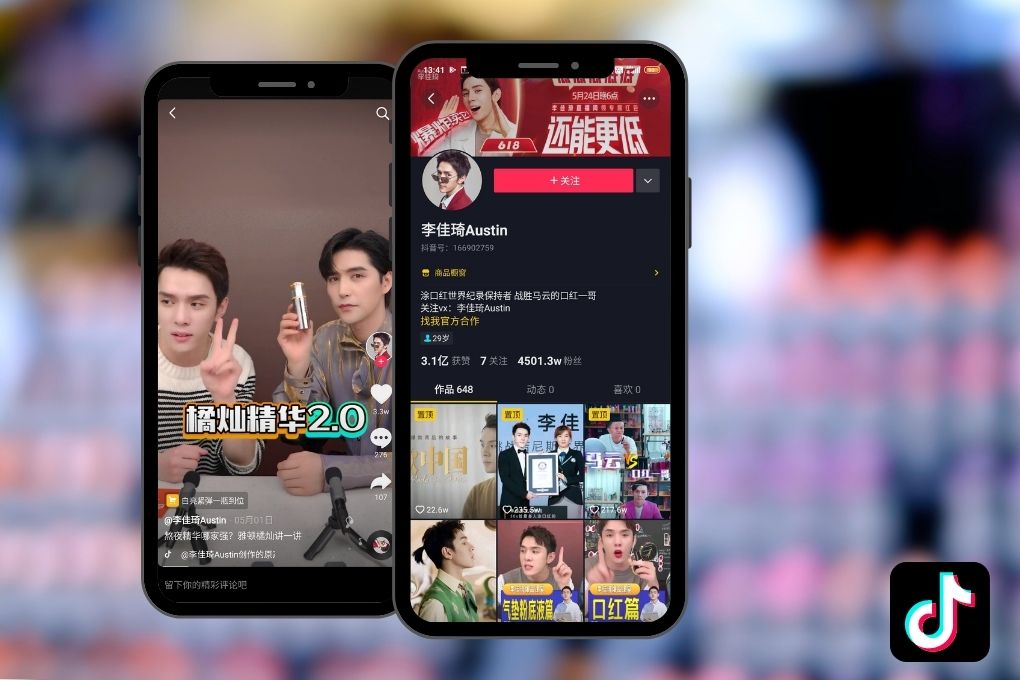
In 2025, Xiaohongshu (RED) became the dominant discovery platform for beauty in China. Brands use a mix of KOL posts, KOC micro-reviews, and UGC (user-generated content) to build trust before consumers convert on Tmall. A single viral “chongcao” (planting grass) post from a trusted creator can drive thousands of units sold within 48 hours. Brands without a Xiaohongshu presence are invisible to the most purchase-ready segment of Chinese beauty consumers.
2025-2026 Market Update
China’s cosmetics sector saw continued growth in 2025 despite global economic pressure. Premium skincare outperformed mass-market products. Ingredient-led marketing, with claims around retinol, niacinamide, and traditional Chinese medicine (TCM) actives like ginseng and tremella, drove purchase decisions. Sustainability claims gained traction among younger buyers in tier-1 cities. International brands that adapted their formulas and messaging to local expectations grew faster than those that simply translated their global assets.
FAQ: What Brands Ask About the Chinese Cosmetics Market
Q: Do we need a local entity to sell cosmetics in China?
Not necessarily. Cross-border e-commerce through Tmall Global or JD Worldwide allows foreign brands to sell into China without registering a local company. You still need CBEC-compliant product registration, but it is faster and cheaper than full NMPA registration. Many brands start this way and open a local entity once sales volumes justify it.
Q: Is Xiaohongshu worth the investment for a small cosmetics brand?
Yes. Xiaohongshu’s user base skews female, urban, and purchase-ready. A targeted KOC strategy with 20 to 50 micro-creators costs less than a single KOL post and often delivers better trust signals. Start with honest product reviews and real use cases. Avoid overly polished content, Chinese consumers respond to authenticity.
Q: How long does it take to see results from a China cosmetics launch?
Realistically, six to twelve months to build brand awareness and generate consistent Tmall traffic. Social seeding on Xiaohongshu and Douyin takes three to four months before conversion rates stabilize. Brands that rush the process without building content and trust first typically underperform during key sales e
Looking for help? Our cosmetics marketing in China can support your brand’s entry into China.