I’ve been working with beauty brands entering China for over 15 years, and German brands have always had something other European players struggle to build: trust. That trust is not marketing. It comes from a genuine reputation for precision manufacturing, clean formulations, and consistent quality. In 2026, that reputation still converts, but the way Chinese consumers discover and buy German cosmetics has changed completely.
China is now the world’s second-largest cosmetics market, with a volume exceeding 500 billion yuan in 2025. The market keeps growing, but the consumers inside it are not the same as five years ago. They are more selective, more informed, and much harder to reach through traditional advertising.
In this post, I’ll explain why German beauty brands still gain ground in China in 2026, what platforms drive their results, and what Cosnova’s example teaches us about executing this market correctly.
The Performance of German Beauty Products in China
China’s economy has produced a new consumer class that wants quality and is willing to pay for it. German brands have been particularly appealing for their high standards, not only in Europe but also in China. That perception of German engineering, applied to beauty, works. Consumers see ingredients lists, certifications, and dermatological validation as signals they can trust.
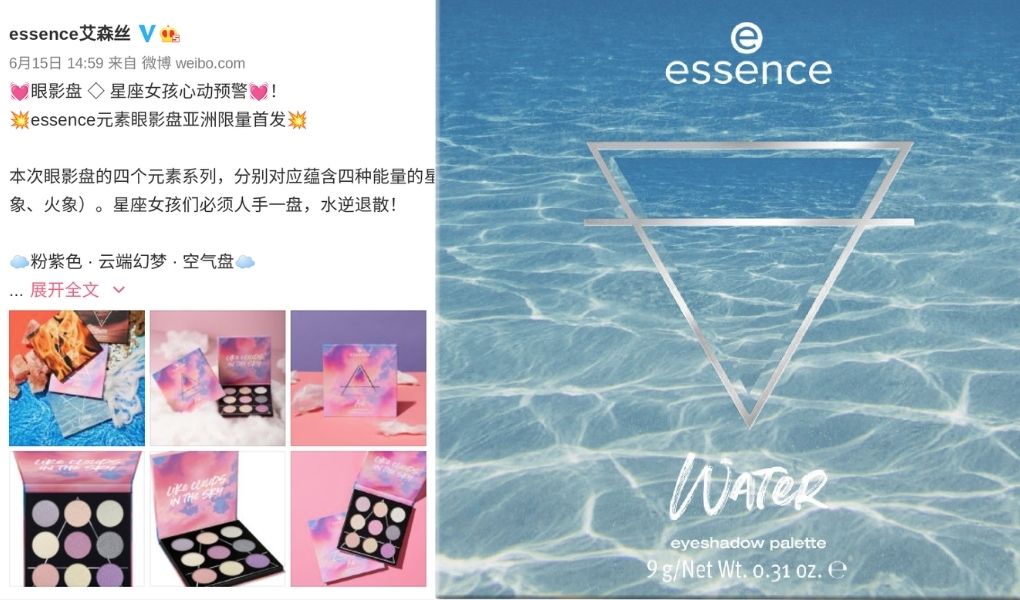
Chinese consumers’ interest in German cosmetics and wellness products held through the pandemic years and accelerated after. During the 6.18 Mid-Year Shopping Festival, German products remained among the most popular items on Tmall Global, Alibaba’s cross-border e-commerce marketplace. In 2025, German beauty brands on Tmall Global saw a 31% year-on-year revenue increase during the 618 festival period, driven mostly by skincare and hybrid makeup-skincare products.
What changed is where sales originate. Five years ago, a brand could launch on Tmall, run a few KOL campaigns, and see results. Today, the path to purchase is longer and more fragmented. Discovery happens on Xiaohongshu or Douyin. Consideration is built through ingredient content and user reviews. Purchase happens on Tmall, JD, or directly through a Douyin shop. German brands that understand this full funnel are the ones growing.
German Beauty Brands are Attractive to the Young Generation in China
With the rise of Generation Z consumers born between 1995 and 2009, more rational young buyers prefer personalized, niche, and high-quality products. In terms of innovation, imported products have played a leading role, filling gaps in the Chinese cosmetics market. Around 2012, South Korea took the lead with BB cream; around 2016, Spanish brand Martiderm triggered a skincare ampoule trend. German brands are now filling a similar gap in the “science-backed drugstore” segment.
This generation does not respond to brand authority alone. They read ingredient lists. They watch dermatologists on Douyin. They share unboxing videos on Xiaohongshu and compare formulations in comment threads. I’ve seen brands with strong German heritage fail in China because they did not create content that matched how these consumers research products.
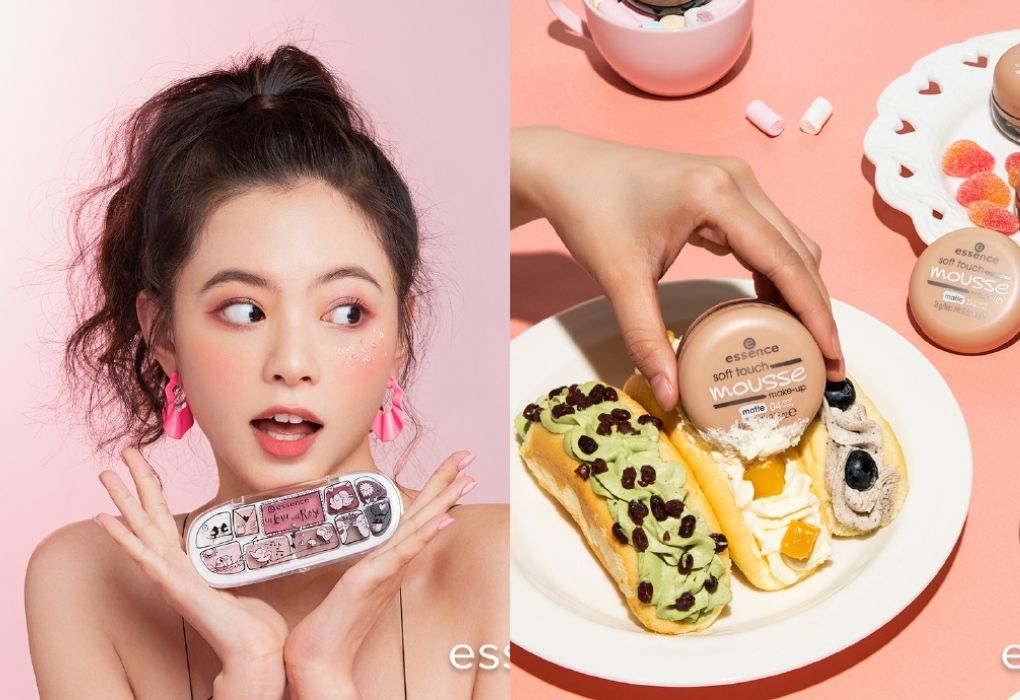
Cosnova understood this early. After testing the market carefully, the company made serious investments to enter China, and during the 2019 shopping festivals the brand grew sales by 25% year on year. That trajectory has continued because they kept investing in content and community, not just in paid distribution.
Ingredient Trends Driving German Brand Growth in 2026
One of the biggest shifts I’ve observed in the past two years is how ingredient-driven purchasing has become. Chinese consumers, especially in the 22-35 age group, now search for products by active ingredient before they search by brand name. Niacinamide, ceramides, panthenol, bakuchiol, these terms get millions of searches on Xiaohongshu every month.
German brands benefit here because their formulations are often clean, dermatologically tested, and ingredient-transparent. Brands that lean into this, publishing detailed ingredient breakdowns, comparison content, and clinical study references, convert better on every platform. In my experience, a German brand with a strong ingredient story and a mid-range price point can outperform luxury French brands in the 18-28 demographic.
The other ingredient trend is “skin barrier” care. Post-pandemic, Chinese consumers became more aware of over-exfoliation and irritation from aggressive products. German pharmacy-style brands, with their focus on gentle efficacy, are positioned well for this shift. Brands working with us have used this angle to build content series on Xiaohongshu that consistently drive traffic to their Xiaohongshu marketing storefronts and Tmall pages.
Social E-Commerce is Booming in China and German Beauty Brands Already Get It
Social e-commerce in China means using platforms like Douyin, Xiaohongshu, and WeChat to drive purchases directly, not just awareness. China leads the world in this model, and in 2026 it is no longer optional for beauty brands. It is the main channel.
Douyin shop revenue for beauty categories grew 44% in 2025. The platform now operates as a full commerce engine: discovery through short video, purchase inside the app, and post-purchase review content that feeds the next discovery cycle. German brands that run Douyin advertising alongside organic KOL content see a compounding effect that pure ad spend cannot replicate.
Xiaohongshu (Little Red Book) remains the most important platform for beauty brand trust-building. In 2026, XHS has over 300 million monthly active users, and 80% of them use it specifically to research products before buying. The algorithm now rewards long-form ingredient content, real user photos, and honest comparison reviews. Brands that produce this kind of content at scale, consistently, see their organic reach multiply without paying for every impression.
AI-Driven Discovery: What Changed in 2025-2026
The biggest platform shift of the past 18 months is AI-driven product recommendation inside Chinese apps. Douyin, Tmall, and XHS all use AI recommendation engines that surface products to users based on behavior, not just search intent. This means a German brand can reach a consumer who has never heard of them, purely because their content matches a behavioral pattern the algorithm has identified.
For brands entering China in 2026, this changes the entry strategy. You no longer need to build brand awareness through expensive campaigns first. You need content that performs well with the algorithm: short videos with clear product demonstrations, before-and-after posts with real skin results, and educational content that keeps users watching or reading.
I’ve worked with German skincare brands that went from zero to 50,000 monthly Douyin followers in four months purely through content strategy, with no celebrity endorsements. The key was producing 20-30 short videos per month, testing formats, and doubling down on what the algorithm rewarded. That approach works because German brand stories, precision, ingredients, clinical testing, give content creators real material to work with.
What German Brands Must Do Right in 2026
Based on what I see with brands working with us today, the ones succeeding do three things consistently.
First, they localize their product story without losing their identity. Chinese consumers want to know why a German formula matters for their skin type, climate, and lifestyle. A brand that just translates its European marketing copy will not perform. One that explains how its ceramide barrier cream helps with the pollution conditions in Shanghai will.
Second, they run Tmall and Douyin in parallel, not sequentially. Cosmetics marketing in China works best when social content feeds search behavior on Tmall. The two channels reinforce each other. Brands that launch on Tmall without a Douyin content strategy see high CPAs and slow organic growth.
Third, they invest in KOC networks, not just top-tier KOLs. Key Opinion Consumers, micro-influencers with 5,000 to 100,000 followers, drive higher purchase conversion rates than celebrities for skincare and makeup. A German brand with a 50,000 euro monthly budget gets better returns from 200 KOCs than from one top-tier celebrity post.
FAQ: German Cosmetics in China
Do German beauty brands need to reformulate for the Chinese market?
Not always. Cross-border e-commerce (Tmall Global, JD Worldwide) allows brands to sell their existing formulations without Chinese NMPA registration. For domestic sales, registration is required and some ingredients may need adjustment.
Which platform should a German brand launch on first?
Start with Xiaohongshu for brand trust, Tmall Global for sales infrastructure, and Douyin for volume. The three work together. Starting with only one slows the whole process down.
How long does it take to see results in China?
With the right content and distribution setup, a brand can see meaningful traction within 3-6 months on Douyin. Tmall growth is slower and depends on reviews, which take time to accumulate. Plan for a 12-month runway to reach sustainable growth.
Contact us for a free consultation on your China cosmetics strategy.