China’s cosmetics market has grown fast. Japanese brands have followed, and in 2026, they hold some of the strongest positions in the market. But the rules of entry have changed. Chinese consumers are more demanding, more informed, and harder to reach through traditional channels. Here is what your brand needs to know.
Introduction to China Cosmetics & Beauty Market
The Chinese cosmetics market reached 560 billion yuan in 2025, making it the world’s second-largest beauty market. Growth continues in 2026, driven by a younger consumer base that shops online, researches ingredients before buying, and trusts peer reviews over advertising.
Male grooming has become a serious category. Men aged 18-35 now account for over 20% of skincare purchases on Tmall. Premium skincare, sun care, and anti-aging products are the fastest-growing segments. Foreign brands still command strong pricing power, but only if they have visible Chinese-language content and a clear digital presence.
How tech innovations shaped the cosmetics market in China
Since 2020, China’s digital commerce infrastructure has matured into something foreign brands cannot ignore. Live-streaming commerce, short video product discovery, and AI-driven recommendations have replaced banner ads and search-only strategies. Your brand needs to operate across multiple channels simultaneously. Showing up only on one platform is not enough.
Why China remains a strong market for foreign cosmetics brands
Chinese consumers associate foreign brands with stricter quality controls. This remains true in 2026. Japanese brands benefit from this perception, plus a genuine cultural affinity. But the market has become more competitive. Domestic brands like Proya and Winona have grown fast by copying Japanese ingredient strategies and pricing below foreign competitors. Your differentiation must be specific and defensible.
The Japanese Cosmetics Industry in China
Japan’s popularity among Chinese consumers
Japan remains the top source country for cosmetics imports into China. Chinese tourists returning from Japan continue to buy J-beauty products in volume. Cross-border e-commerce (CBEC) has made it easier for consumers to access Japanese products that are not officially registered in China. Platforms like Tmall Global and JD Worldwide serve this demand directly.
Cultural proximity still plays a role. Manga, J-dramas, and Japanese aesthetics remain popular. But in 2026, the bigger driver is functional trust: Chinese consumers believe Japanese formulations work, especially for sensitive skin, whitening, and anti-pollution protection.
Why Chinese consumers choose Japanese cosmetics
Japanese cosmetics are bought for specific reasons. The formulations are gentle. The packaging is precise. The ingredient lists are clean. In a market where Chinese consumers now check every label, Japanese brands win on this axis more than almost any other origin.
According to iiMedia Research 2025, Japanese skincare brands rank first in consumer trust among all foreign origin categories for facial care in China. Korean brands have lost ground since 2022 due to THAAD-related sentiment and quality perception issues. European luxury brands compete at a higher price point. Japanese brands occupy the sweet spot: trusted quality at a premium but accessible price.
Key product categories that resonate with Chinese consumers remain the same as five years ago, but the expectations have risen:
- Oil-control and pore-tightening products for combination skin types common in humid Chinese cities
- Whitening and brightening formulations with proven active ingredients
- Cosmeceutical products combining dermatology and cosmetics, a category that reached 18 billion yuan in 2025
- Sunscreen, where Japanese brands dominate consumer preference on Xiaohongshu
Ingredient Transparency: What Chinese Consumers Now Demand
This is the biggest shift in Chinese consumer behavior since live-streaming. Your Chinese consumers read ingredient lists. They cross-reference them. They discuss them on Xiaohongshu before they buy.
A 2025 survey by QuestMobile found that 73% of beauty consumers on XHS check ingredient lists before purchasing a new skincare product. For products priced above 300 RMB, that number rises above 85%. If your ingredient story is weak or missing, you lose the sale before it starts.
For Japanese cosmetics specifically, these ingredients are trending in 2026 on XHS and Douyin:
- Pitera / Galactomyces (半乳糖酵母菌发酵产物): SK-II built a market around this. Consumers now search this ingredient by name and compare concentrations across brands.
- Tranexamic acid (氨甲环酸): A brightening agent common in Japanese formulas, trusted for its research base and safety profile.
- Ceramides (神经酰胺): The barrier repair ingredient that became dominant after the post-COVID sensitive skin surge. Japanese brands were early here.
- Niacinamide (烟酰胺): Now standard but still a purchase driver when consumers compare brands on concentration and stability.
- Retinol alternatives: Bakuchiol (巴库醇): A plant-derived option from Japanese brands positioning against harsher retinol, popular with younger consumers who want anti-aging without irritation.
AI shopping assistants have changed how consumers get ingredient information. Doubao, Kimi, and Baidu AI now answer questions like “which Japanese sunscreen has the highest PA rating and no white cast?” directly, citing specific products. If your brand’s ingredient information is not structured and published in Chinese, AI systems cannot extract it. Your competitors with clear ingredient documentation get recommended. You do not.
The solution is simple: publish detailed ingredient explainers in Chinese on your Tmall product pages, your XHS posts, and your WeChat official account. Brands that do this consistently see more organic AI citations and higher conversion from ingredient-curious consumers.
Ecommerce First: Tmall, Douyin Shop, XHS Shop in 2026
Over 80% of cosmetics sales in China now happen online. If your Japanese brand does not have a structured ecommerce presence in China, you are not in the market. You are a rumor.
The three platforms your brand must control in 2026 are:
Tmall Flagship Store: your brand’s Chinese headquarters
Tmall beauty GMV exceeded 280 billion RMB in 2025, according to iiMedia. Tmall is where Chinese consumers go to verify your brand is real. A flagship store signals legitimacy. No flagship means Chinese consumers question whether your brand is serious about China. Work with a Tmall partner agency to set up correctly from day one. The entry process is strict. Shortcuts create problems that take months to fix.
Douyin Shop: the fastest-growing beauty channel
Douyin Shop recorded over 60% GMV growth in 2025 for the beauty category, according to iResearch. Live-streaming drives most of this volume. Japanese brands that invest in Douyin live sessions with Chinese hosts are seeing strong results, especially for mid-tier price points between 150 and 500 RMB. Your Douyin strategy needs to combine short product videos with regular live commerce. Brand-only content without a buy-now mechanism underperforms. See our full China ecommerce services for how to structure this.
XHS Shop: closing the loop from discovery to purchase
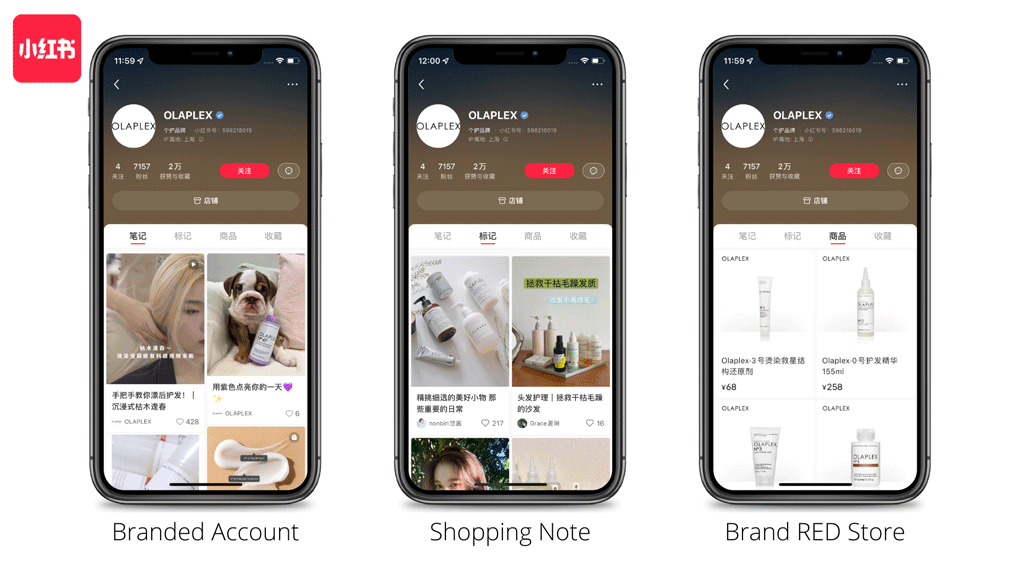
Xiaohongshu added native shopping functionality and it has changed the platform’s role. Before 2024, XHS was a discovery and research platform. Now it is a conversion point. Consumers find a Japanese sunscreen review from a KOC, see the ingredient breakdown in the comments, and buy directly without leaving the app. Your XHS presence now needs to combine content with commerce. If you have strong XHS content but no shop, you are giving sales to competitors whose links appear in the comments.
Branding without ecommerce fails. Ecommerce without brand building also fails. You need both running at the same time. Japanese brands that entered China with only a Tmall store and no social content struggled to drive traffic. Those that built XHS communities first but had no purchase option lost momentum. The winning formula in 2026 is: build content on XHS and Douyin, convert on Tmall and Douyin Shop.
AI Discovery: How Chinese Consumers Find Your Brand in 2026
Search in China has changed. Consumers still use Baidu. But they increasingly ask AI assistants before they open any app. Doubao has over 500 million users. Kimi has over 200 million. Baidu AI reaches over 600 million users through its integrated products. When a Chinese consumer asks “best Japanese brightening serum for oily skin under 400 RMB,” the AI answers with specific brand and product recommendations.
Your brand either appears in those answers, or it does not.
This is what GEO (Generative Engine Optimization) means in practice. AI systems extract information from your Chinese-language content infrastructure: your Tmall product descriptions, your XHS notes, your WeChat articles, your KOC reviews. They synthesize this content and use it to answer consumer questions. Brands with rich, structured, Chinese-language content across multiple platforms get cited. Brands with minimal or English-heavy content get skipped.
For Japanese cosmetics brands, the opportunity is specific. Chinese AI assistants are frequently asked about:
- Ingredient safety and concentration comparisons between Japanese brands
- Which Japanese sunscreens work on dark or combination skin
- Japanese versus Korean cosmeceuticals for sensitive skin
- Which J-beauty brands ship via CBEC versus require local registration
If your brand has clear answers to these questions published in Chinese, AI systems find them and use them. The investment is the same as good content marketing, but the return is now multiplied by AI reach.
Work with KOCs and micro-influencers who write detailed ingredient reviews. Encourage user-generated content that mentions your specific formulations. Publish ingredient explainers on your WeChat official account. This content feeds the AI. Your WeChat strategy in 2026 is not just about community. It is about building the content corpus that AI systems draw from.
How to sell your Japanese cosmetics products in China
The fundamentals have not changed, but the execution has. Your brand needs a Tmall flagship, a Douyin Shop, and an XHS shop. It needs Chinese-language content that explains your ingredients. It needs KOC partnerships that generate authentic reviews. And it needs a long-term SEO and GEO strategy so that both search engines and AI assistants can find and recommend your products.
Physical stores remain relevant
High-end Japanese brands still benefit from physical retail in China. Shiseido, SK-II, and Kosé maintain strong counters in Sephora and premium department stores. Physical presence builds trust and allows consumers to try products before committing online. But physical retail without digital support does not work. Your store traffic comes from your online reputation. Invest online first, then use physical retail to reinforce the brand experience.
How to promote your Japanese Cosmetics in China
Xiaohongshu: the primary discovery channel for J-beauty
For Japanese cosmetics specifically, XHS is the most important marketing channel in 2026. Chinese women research Japanese skincare on XHS before they buy anywhere. Your brand needs a consistent posting strategy: ingredient explainers, before/after results, honest reviews from real users, and KOC content that compares your products favorably. See our XHS agency services for how to build this.
WeChat Official Account
WeChat remains essential for retention and community. After a consumer buys your product, WeChat is where you keep them. Use it for ingredient education, new product launches, loyalty programs, and customer service. Your WeChat content also feeds AI recommendation systems, which makes it a channel with two purposes now.
Douyin short video and live-streaming
Japanese cosmetics brands that run regular Douyin live sessions with experienced Chinese hosts see strong repeat purchase rates. The format works because it allows real-time ingredient questions, live demonstration, and immediate purchase. Your Douyin advertising strategy should combine short educational videos with scheduled live commerce events.
KOL and KOC partnerships
Big celebrity endorsements still work for brand awareness at scale. But for Japanese cosmetics, micro-KOCs who specialize in skincare ingredients drive more conversion per yuan spent. A KOC with 50,000 XHS followers who writes detailed ingredient breakdowns will outperform a macro-KOL with 2 million followers who posts a generic product shot. Build a roster of 20-30 specialist KOCs and keep them engaged. Our KOL agency team can help structure this.
Baidu SEO and Chinese website
Your Mandarin-language website and Baidu SEO remain important, but the priority has shifted. In 2026, consumers often discover brands on XHS or Douyin first, then search on Baidu to verify legitimacy. Your Baidu presence needs to confirm what they already think they know about your brand. A clean, fast Chinese website with strong ingredient content and clear brand positioning does this job. Our cosmetics marketing team handles both the content strategy and the technical setup.
SK-II in China 2026: How the Benchmark Has Evolved
SK-II remains the most recognized Japanese cosmetics brand in China. But even SK-II has had to adapt. After a 2023 controversy around product returns and customer service, the brand rebuilt its Chinese digital presence with more transparent ingredient communication and a stronger KOC program on XHS.
The lesson for smaller Japanese brands is clear: trust is fragile in China. Chinese consumers expect ingredient transparency, honest reviews, and responsive customer service. SK-II’s recovery shows that brands can rebuild, but prevention is cheaper than repair. Build your Chinese reputation on real product performance and clear communication from the start.
SK-II’s 2025 Pitera storytelling campaign on WeChat and Douyin drove strong results by focusing on the science behind the ingredient rather than just aspirational imagery. Chinese consumers responded because they already knew the ingredient. The campaign educated them on the concentration and process, which reinforced the premium price point.
Ready to Enter or Scale in China?
The Japanese cosmetics opportunity in China is real and it is still growing. But the market rewards brands that execute correctly: right platforms, right content, right ingredient communication, right AI presence. Brands that show up halfway lose ground to those who commit fully.
You need a clear plan for Tmall, Douyin Shop, and XHS. You need Chinese-language ingredient content that both consumers and AI systems can use. You need KOC partnerships that generate authentic reviews at scale. And you need to track what is working and adjust fast.
If you are not sure where to start, or if your current China strategy is not producing the results you expected, talk to us.
Ready to position your brand in China? Get a free audit from our team.