
Local Chinese beauty brands are growing fast, driven by digital platforms, rising disposable income, and a new generation of consumers who trust homegrown names. China’s domestic cosmetics brands have been gaining ground with Chinese women, while international players are being forced to rethink their positioning. The gap between local and foreign brands is narrowing faster than most Western executives expected.
Western brands now represent under 25% of China’s makeup market
Kantar data showed that Chinese domestic beauty brands held around 55% of the market as of the mid-2020s. By 2026, that figure has stabilized above 60% across mass and mid-range segments. Domestic growth is driven by online sales, aggressive pricing, and better product formulation. Western brands now account for under 25% of China’s cosmetics market, down from 40%+ a decade ago. Korean brands, once dominant, are holding around 8-10% following years of geopolitical tension affecting consumer sentiment.
Three out of the top ten cosmetics brands by sales on Singles’ Day in recent years have consistently been domestic Chinese names. Classic brands like Pechoin (Pechora) continue to lead in skincare basics, while newer domestic players capture younger urban consumers with trend-driven campaigns on Douyin and Xiaohongshu. For an overview of where the market is heading, see our 10 Key Trends of the Chinese Cosmetics Market.
5 trends shaping the Chinese cosmetics market in 2026
- Guochao (national pride) beauty: consumers actively seek out Chinese heritage brands, especially among 18-35 year olds in tier-1 and tier-2 cities.
- Skincare over makeup: facial skincare (serums, SPF, repair creams) is outgrowing color cosmetics. Functional claims backed by dermatology drive purchase decisions.
- Live commerce dominance: Douyin live-streaming accounts for over 30% of beauty sales online. A single KOL live session can move 10,000+ units in hours.
- Clean and “green” labeling: ingredient transparency is now a purchase driver. Brands like Clarins and Novexpert, which Olivier VEROT has supported in China, benefit directly from this trend with their natural-origin positioning.
- Lower-tier city expansion: tier-3 and tier-4 cities are the growth frontier. Digital-native consumers there rely entirely on social platforms for beauty discovery.
Playing up e-commerce channels has been the key to growth
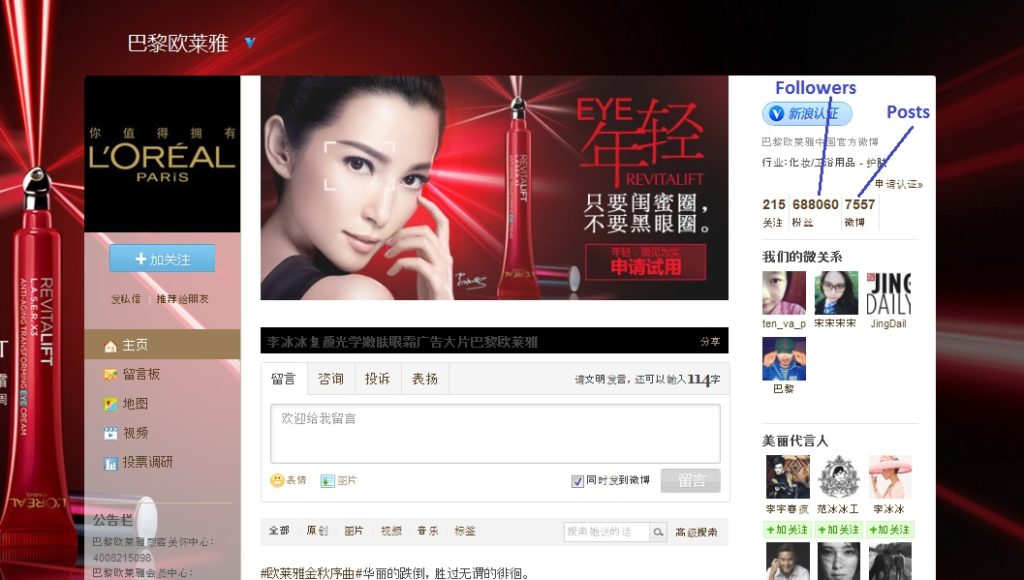
E-commerce is not just a sales channel but also a key awareness and discovery driver for both local brands and foreign ones targeting Chinese consumers. Domestic brands moved fast on Tmall, JD, and Pinduoduo. They offered better value packs, faster delivery, and localized promotions. International brands that failed to adapt their pricing or product range to online formats lost shelf space they will not easily recover.
Domestic brands still face a ceiling in the premium segment. First-tier city consumers in Shanghai and Beijing continue to prefer international names they associate with quality and status. Foreign beauty brands get extensive coverage in Chinese beauty blogs and online communities, while local brands remain underrepresented in premium editorial content. Working with Influencers and KOLs in China is now the standard way to close that perception gap.
Xiaohongshu (XHS) and UGC: where cosmetics discovery happens
Xiaohongshu, known as Little Red Book or RED, has become the most influential platform for cosmetics discovery in China. With over 300 million registered users and a core audience of urban women aged 18-35, XHS operates like a visual search engine for beauty. Users post detailed product reviews, before-and-after photos, ingredient breakdowns, and “shelfie” content that directly drives purchase intent on Tmall and JD.
User-generated content (UGC) on XHS outperforms brand-produced content in almost every category. A post from a regular user with 5,000 followers showing a skincare result converts better than a polished brand campaign. This is why working with a Little Red Book Agency for Beauty Brands in China is now a standard strategy for cosmetics brands that want real traction with Chinese consumers.


