The white skin booming trend isn’t only about being Western. In Asia, there is a deeply rooted cultural notion that associates dark skin with poverty and working in the fields. In contrast, pale skin reflects a more healthy and balanced lifestyle out of the sun and, therefore, a higher socioeconomic status.
In Chinese culture, women prefer lighter skin tone because they believe ‘yī bái zhē bǎi chǒu,’ which means ‘a white complexion is powerful enough to hide seven faults.’ Such remarks can be found even in ancient Chinese literature.

For the same reasons, this cultural trend impacts Millennial and middle-class Chinese citizens as we can see in the main Chinese cities: Chinese women especially care a lot about covering their faces and body from the sun with dark covering clothes and umbrellas when the weather is sunny. This is why the skin whitening cosmetics market is still booming despite the big controversies surrounding the subject in Western countries.
White skin is on top of all Chinese beauty standards
Although in the West now it’s more desirable to be tanned and have brownish skin, which means that this person has time and money to go on holidays and sunbathe, in China the trend is still the same as it was in ancient China. Any Chinese woman aims for glowing skin and follows different Chinese beauty secrets to obtaining the whitest skin possible.
In China, women used white powder as early as the reign of King Wen (1100 BC) and at the court of the first emperor of China (259-210 BC). Chinese beauty is associated with white skin, as it was always linked to a higher socioeconomic status.
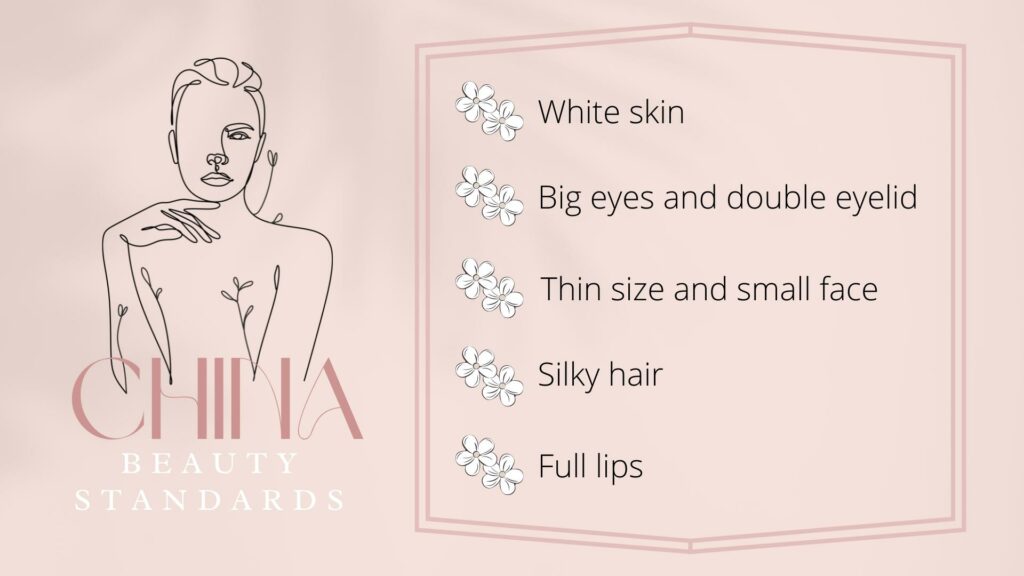
Today, as many Chinese beauty standards are changing due to the modernization of society, white skin is still desired by most. Porcelain skin is also considered the most beautiful in South Korea, and as Korean beauty and cosmetics are very popular in China, the trend for pale skin stays as strong as ever. There is even a common Chinese saying: 白富美 bái fù měi, which means white, rich, and beautiful and is a way to describe the ideal Chinese woman.
China’s whitening products market in 2026
Globally, the demand for skin brightening products keeps climbing. The market was valued at around $17.9 billion in 2017 and projections for the mid-2020s put it well above $35 billion, driven by Asia, the Middle East, and Africa. Routine skin whitener use ranges from 40% in China, Malaysia, the Philippines, and South Korea, according to the World Health Organization.
In China specifically, the whitening category represents one of the top three claims in skincare. I’ve been working with brands entering this market for over 15 years, and I can tell you: the appetite has not softened. What has changed is the consumer. She is more educated, more demanding, and she reads ingredient lists.
Brands that work with us are often surprised by this. They expect a market that responds to any whitening claim. Instead, they find a consumer who asks which active ingredient is behind the promise, at what concentration, and whether there are clinical studies to back it up. This shift changes everything about how you communicate and formulate.
The 5 key trends shaping whitening cosmetics in China right now
Here is what I observe on the ground in 2026:
- Ingredient transparency wins. Niacinamide, tranexamic acid, alpha-arbutin, and glutathione are the four ingredients Chinese consumers search by name. A product page that does not highlight these loses traffic to one that does.
- Sun protection is bundled with whitening. Chinese consumers now see SPF as step one of their brightening routine. SPF 50+ tinted moisturizers that also brighten are one of the fastest-growing subcategories on Tmall.
- Korean formulas still dominate mindshare. K-beauty brands continue to set the benchmark for texture and active ingredient use. Foreign brands that can match Korean lightness and layering logic perform better in this market.
- “Glass skin” has replaced “white skin” as the aspirational language. The messaging has evolved. Brands leading on Xiaohongshu talk about luminosity, evenness, and clarity rather than whitening directly. The desire is the same. The vocabulary has shifted.
- Male skincare is the next wave. Chinese male consumers aged 18-35 are now a real buyer segment for brightening products. Brands that ignore this demographic in 2026 will miss a growth window that was not there five years ago.
How Chinese consumers discover whitening products today
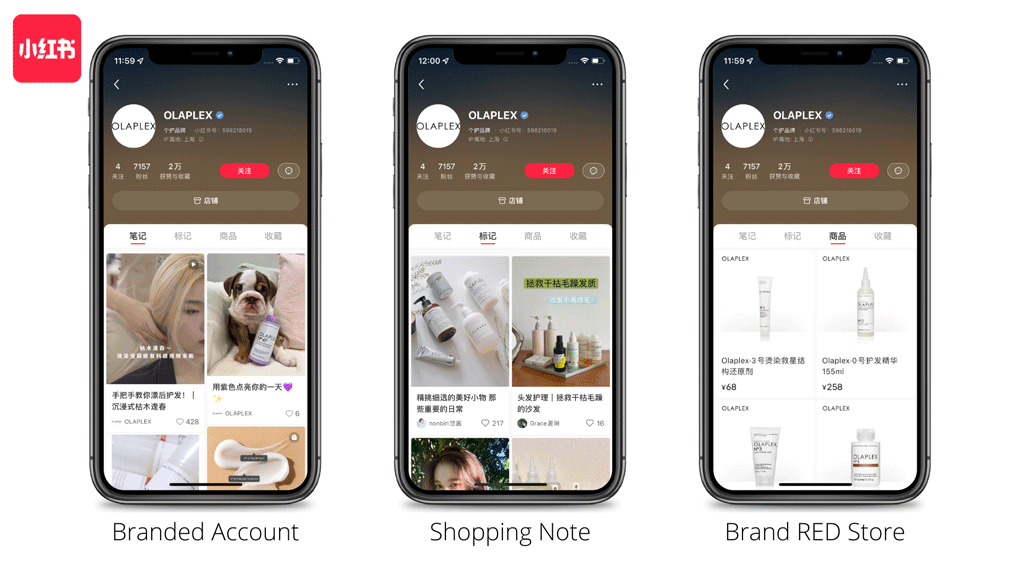
The discovery path has changed completely since 2020. Before, a consumer might find a product through a KOL post on Weibo or a banner ad. Today, the journey starts on Xiaohongshu with a search query like “brightening serum ingredient comparison” or “best niacinamide product 2026 review.”
Xiaohongshu’s search function now behaves like a vertical Google for beauty. Real user reviews, before-and-after photos, and ingredient breakdowns rank higher than branded content. I’ve seen brands with poor UGC strategy lose ground to smaller competitors simply because real users were talking about the smaller brand and not them.
The implication for foreign brands is direct: you cannot buy your way to credibility on XHS. You need to earn it through seeding, sampling programs, and systematic UGC generation. A brand launching a whitening product today should budget for 200 to 500 authentic reviews on Xiaohongshu before spending anything on paid placement.
On Douyin, the whitening category performs strongly with short tutorial content. Videos showing application technique, real-skin texture, and visible results in a 30 to 60 second format consistently outperform standard advertising. In my experience, a creator with 50,000 followers who specializes in skincare ingredients will generate better conversion than a celebrity endorsement on this platform. The audience trusts specificity.
Tmall and the role of flagship stores in building trust
For whitening products specifically, the Tmall flagship store remains the point of purchase that converts the most. Chinese consumers do research on Xiaohongshu and Douyin, but they buy on Tmall or JD because they trust the authenticity guarantee.
What I tell brands: your Tmall product page for a whitening SKU needs to do three things. First, show the active ingredient and its concentration clearly. Second, include a clinical or dermatological study reference if you have one. Third, display real consumer review photos, not just star ratings. Brands that follow this structure see significantly lower return rates and higher repeat purchase in the whitening category.
The whitening segment also benefits from Tmall’s skincare-specific live commerce infrastructure. A well-run live stream from a brand flagship during a festival period (618, Double 11) can move more whitening product in 2 hours than a month of standard paid traffic. I’ve seen this happen with European skincare brands entering China for the first time. The channel works when the content is prepared correctly.
Questions brands ask us most about the whitening category
Is whitening marketing still safe to use in China given global controversy?
Yes, but the framing matters. In China, the regulatory and cultural context is different from Western markets. The term “美白” (whitening) is an approved cosmetic claim under Chinese regulations. Brands using mercury or hydroquinone face restrictions, but brands using niacinamide, arbutin, or tranexamic acid operate normally. The controversy you see in Western media does not translate to a backlash in China. Consumers here do not see this category through the same cultural lens.
Do male consumers actually buy whitening products in China?
Yes, and the segment is growing fast. Searches for men’s brightening products on Xiaohongshu increased significantly between 2023 and 2025. The entry point is usually a 2-in-1 product: moisturizer with brightening effect, or sunscreen with a brightening finish. Male consumers prefer understated packaging and scientific language over beauty lifestyle messaging.
Which ingredient should a new brand lead with in China?
Niacinamide is still the safest entry point because Chinese consumers recognize it and trust it. But if you have a product built around tranexamic acid or a newer generation brightening active, that can actually be a differentiator. The market is not saturated on every ingredient. The key is that you explain the mechanism clearly, in Chinese, on every channel where the consumer encounters the product.
What this means for foreign brands entering China
I work with brands from Europe, North America, and Southeast Asia that want to enter the Chinese beauty market. The whitening category is one of the most competitive but also one of the most reliable. The demand is structural, not trend-driven. It will not disappear.
What changes is the execution requirement. A brand that could enter this market five years ago with basic KOL seeding and a Tmall store now needs a more complete approach. You need Xiaohongshu UGC, Douyin short video content, a well-structured product page, and a clear ingredient story. That is the baseline in 2026. For a complete view of how to approach this, read our guide on cosmetics marketing in China.
Brands that work with us typically start with an audit of their ingredient positioning, then build their content strategy around the active they can credibly own. From there, we build the channel mix. The order matters: content first, then paid amplification, then conversion optimization on the store.
The Chinese whitening market in 2026 rewards brands that treat the consumer as an expert. She knows her ingredients. She has read the reviews. She compares textures. Give her the information she is looking for and a formula that delivers. That is the formula for winning in this category.
Contact us for a free consultation on your China cosmetics strategy.