

Chinese eCommerce platforms have changed faster in the last two years than in the previous decade. The biggest players remain Tmall, JD.com, Pinduoduo, and Taobao, but the real action in beauty has shifted. China’s eCommerce market now exceeds 2 trillion dollars in 2026, and beauty is one of the fastest-growing categories. I’ve been working with international cosmetics brands entering this market for 15 years. The platforms I recommend today look different from what I recommended in 2021. This guide reflects where the money actually moves in 2026.
In this article, I’ll walk you through the key eCommerce platforms in China, what each one does best for beauty brands, and where I see brands winning right now. Whether you’re launching for the first time or trying to grow an existing presence, understanding the platform landscape is step one.
Key Takeaways
- China’s eCommerce market accounts for over 50% of all global online retail transactions in 2026, with beauty ranking among the top three categories.
- Tmall Global and JD Worldwide remain the gold standard for cross-border entry, but Douyin eCommerce has become the fastest-growing channel for beauty brands in China.
- Brands that work with us consistently find that Xiaohongshu drives discovery while Tmall or Douyin closes the sale. The two-platform strategy is now standard for cosmetics.
- AI-powered recommendation algorithms now shape how Chinese consumers find beauty products. Brands without consistent content on XHS and Douyin are invisible to new buyers.
- WeChat stores and Xiaohongshu shopping have matured into serious revenue channels, not just brand awareness tools.
China eCommerce in 2026: What Has Actually Changed
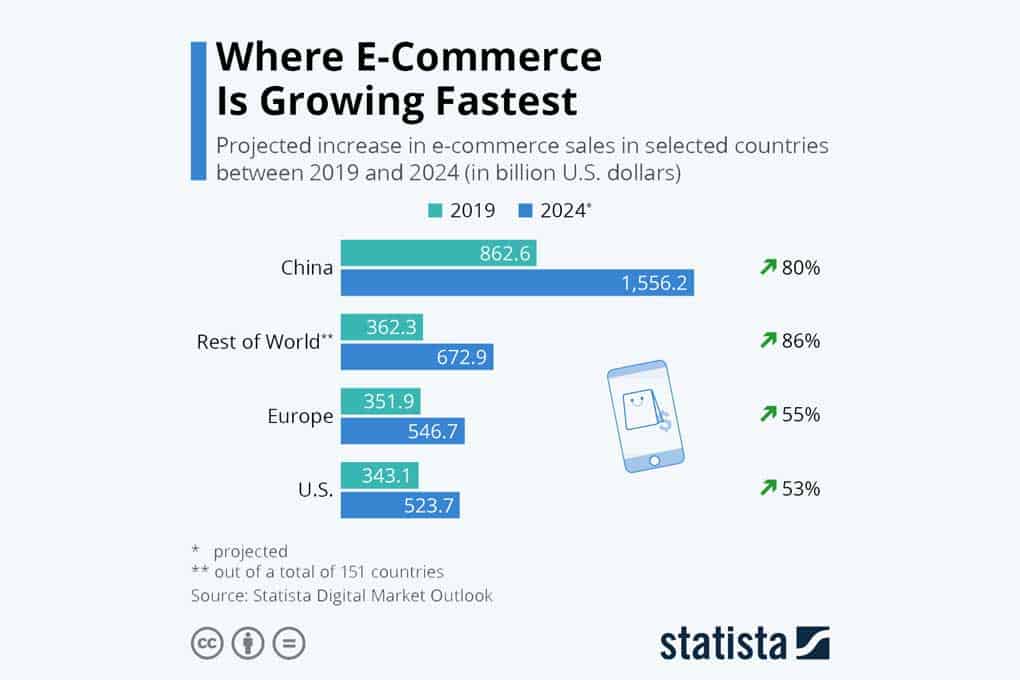
China’s eCommerce didn’t just grow since 2019. It restructured. The old model, where brands listed products on Tmall and bought traffic through paid search, still works. But it’s no longer enough on its own.
Three things changed the game for beauty brands specifically.
First, content-driven commerce took over. Chinese consumers aged 18-35 don’t search for products the way Western shoppers do. They discover them through short videos on Douyin, through reviews on Xiaohongshu, and through live streams hosted by KOLs. If your brand isn’t present in those spaces, your Tmall store will struggle to generate traffic organically.
Second, AI-powered recommendation algorithms now dominate product discovery. Both Douyin and XHS push products to users who have never searched for them, based on behavioral data. I’ve seen international skincare brands go from zero to 10,000 monthly orders in three months because their content hit the algorithm at the right moment. That wasn’t possible in 2020. Brands that build content libraries with consistent posting schedules get rewarded.
Third, ingredient transparency became a purchase driver. Chinese consumers in 2026 read labels. They know what retinol, ceramide, niacinamide, and fermented extracts do. They compare. Brands that lead with clear ingredient communication, in Chinese, backed by certifications and KOL education content, convert better than brands that lead with lifestyle imagery. I’ve watched luxury fragrance brands lose ground to mid-range serums simply because the serum brand educated its audience better.
Why China’s eCommerce Market Matters For Beauty Brands
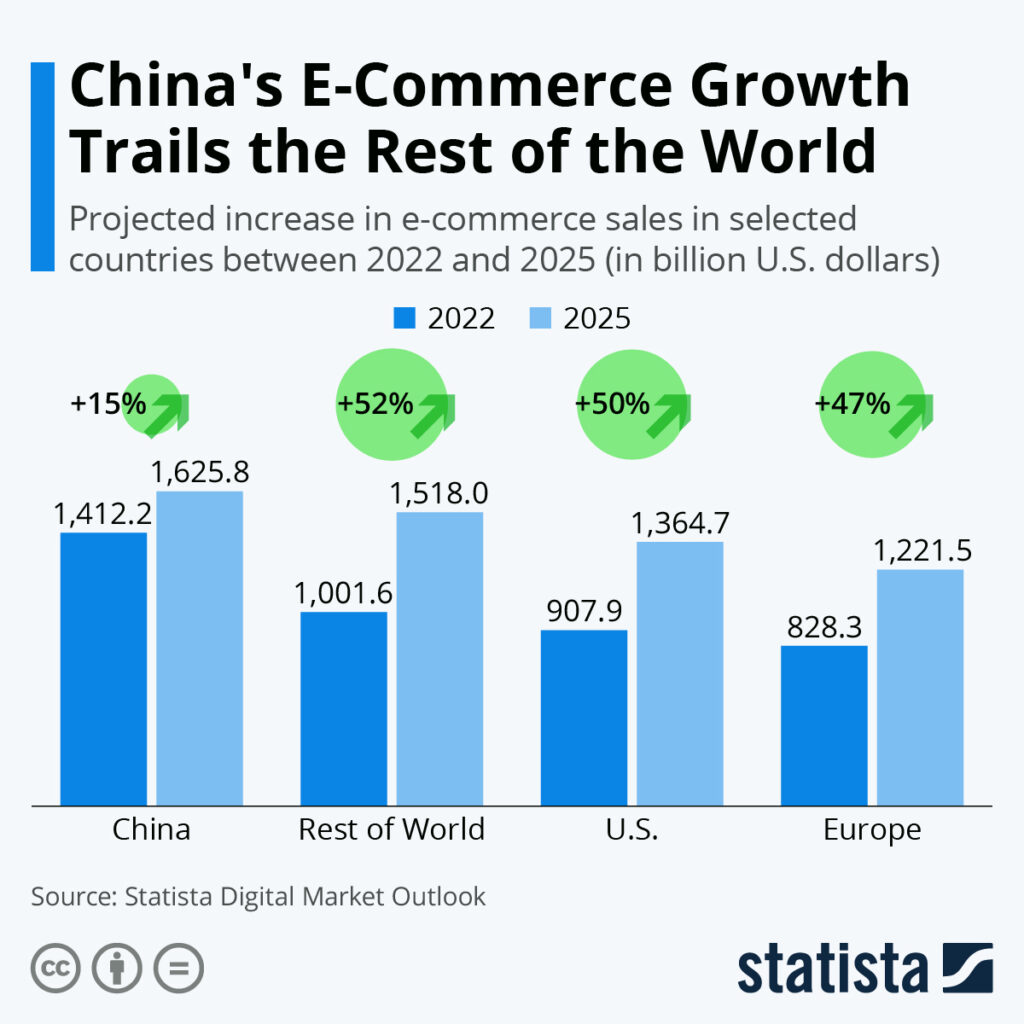
Companies selling products on Chinese eCommerce platforms can increase their sales by 20-30% year over year when they execute correctly. China accounts for nearly 50% of all eCommerce transactions worldwide. No other single market offers that concentration of digital buyers.
For cosmetics specifically, the numbers are clear. The Chinese beauty market reached 85 billion USD in 2025 and continues to grow at 8-10% annually. Skincare leads, followed by color cosmetics and fragrance. The premium and super-premium segments are growing faster than mass market, which is good news for European and American brands with strong positioning.
One key aspect that sets China apart from other markets is its fully integrated approach where search, social, and retail connect directly. A user on Douyin watches a 30-second tutorial, taps a product link in the video, and completes a purchase without leaving the app. That entire journey can happen in under two minutes. No other market has built this kind of infrastructure at scale. See our full guide on cosmetics marketing in China for more context on how this affects brand strategy.
To legally sell through eCommerce in China, operators must function as registered legal entities, either through a Chinese entity or via cross-border eCommerce channels. Most international beauty brands start with CBEC through Tmall Global or JD Worldwide before setting up a local entity.
The Top Chinese eCommerce Platforms for Beauty Brands
Tmall and Tmall Global
Tmall remains the first choice for premium beauty brands entering China. It carries a trust signal that no other platform matches. Chinese consumers associate Tmall flagships with authenticity and brand credibility. If you’re selling skincare or color cosmetics above 200 RMB per unit, your brand needs to be on Tmall.
Tmall Global handles cross-border sales. Brands can ship from bonded warehouses in free-trade zones without needing a Chinese business license at entry stage. The trade-off is higher logistics costs and slightly longer delivery times compared to domestic fulfillment. In 2026, Tmall has pushed brands harder to integrate live streaming and short video content directly into product pages. Static listings underperform. The platform now surfaces video-rich pages more aggressively in search results.
Working with a Tmall partner agency for beauty brands is the fastest way to get your store set up correctly, avoid the common compliance mistakes, and connect to the right KOL network for launch. See our detailed breakdown at Tmall China for beauty brands.
Douyin eCommerce
Douyin is where beauty brands are growing fastest in 2026. The platform had over 700 million daily active users as of early 2026, and its eCommerce GMV for beauty and personal care surpassed 400 billion RMB last year. Those numbers get attention.
What makes Douyin different is the discovery model. On Tmall, users search for your brand by name. On Douyin, the algorithm serves your content to users who have never heard of you, based on their behavior. A brand I worked with in early 2025 launched a series of 15-second skincare education videos featuring their retinol formula. Within six weeks, their Douyin store had generated more revenue than their first year on Tmall. That’s not unusual now.
Live streaming is central to Douyin commerce. Brands that run daily live streams, even short ones, outperform brands that rely only on pre-recorded content. For cosmetics, live streams allow real-time product demonstrations, ingredient Q&A, and flash promotions. This format works especially well for skincare and foundation where texture and application matter to the buyer. Read our full guide on Douyin advertising for beauty brands.
Xiaohongshu (Little Red Book)
XHS is where Chinese consumers, especially women aged 18-35, go to research beauty purchases. It functions as a combination of Instagram, Google, and product review forum. In 2026, XHS has over 300 million registered users and processes tens of millions of beauty-related searches daily.
XHS shopping features are now mature. Brands run official accounts with linked product pages. KOL posts tag products directly. Users complete purchases without leaving the app. The conversion path from content to sale is shorter than it was two years ago.
For cosmetics brands, XHS serves two functions. First, brand building through organic content and KOL posts. Second, direct sales through the XHS store. Brands that work with us on Xiaohongshu marketing typically see their XHS presence drive significant traffic to Tmall or Douyin stores, even before the XHS store generates direct sales. The platform works as a trust-builder that supports every other channel.
JD.com
JD.com is China’s second-largest eCommerce platform by market share. It is known for fast domestic logistics and a reputation for authentic products. JD’s customer base skews slightly older and more male than Tmall’s, which makes it less central for most cosmetics brands. However, for skincare brands targeting the 35-50 age bracket, or for brands with a strong male grooming line, JD performs well.
JD Worldwide handles cross-border sales, similar to Tmall Global. For cosmetics brands with limited marketing budgets, I usually recommend prioritizing Tmall and Douyin before adding JD to the mix.
Pinduoduo
Pinduoduo built its reputation on group buying and deep discounts. It remains the dominant platform for price-sensitive consumers in lower-tier Chinese cities. For most premium cosmetics brands, Pinduoduo is not the right starting point. The platform’s user base expects low prices, and competing on price in beauty on Pinduoduo can damage brand positioning on other platforms.
That said, some brands use Pinduoduo strategically to move end-of-line stock or to test price-sensitive segments. If you’re running a mass-market beauty line or want to build volume in tier 3-4 cities, Pinduoduo deserves consideration.
WeChat Stores and Private Traffic
WeChat remains central to Chinese digital life with 1.3 billion monthly active users. WeChat stores allow brands to sell directly through Mini Programs within the app. The traffic on WeChat is private, meaning it comes from your existing followers and CRM contacts rather than from algorithmic discovery.
WeChat works best as a retention and loyalty channel. Brands that build a WeChat community, using WeCom for private traffic management, generate repeat purchases from existing customers at very low acquisition cost. I’ve seen beauty brands drive 30% of their total eCommerce revenue through WeChat alone, from a customer base built over two to three years.
Platform Strategy for Cosmetics Brands in 2026
The brands winning in China right now are not on one platform. They run a coordinated strategy across three or four channels. A typical setup looks like this: XHS for brand discovery and education, Douyin for content-driven sales and new customer acquisition, Tmall as the brand flagship and trust anchor, WeChat for retention and repeat buyers.
The ingredient story runs across all channels. Brands that invest in Chinese-language educational content about their formulas, backed by clinical data or certifications, outperform brands that lead with heritage or packaging alone. Chinese consumers in 2026 are sophisticated. They compare ingredient lists. They watch KOL breakdowns of formulas. If your product cannot explain clearly why it works, it will lose to a local brand that can.
For brands ready to move, the starting point is usually Tmall Global plus a 90-day XHS content campaign. That combination builds the trust and search presence needed before investing in Douyin live streaming. The sequence matters. Our guide on how to sell cosmetics in China covers the full channel strategy in more detail.
Contact us for a free consultation on your China cosmetics strategy.


