
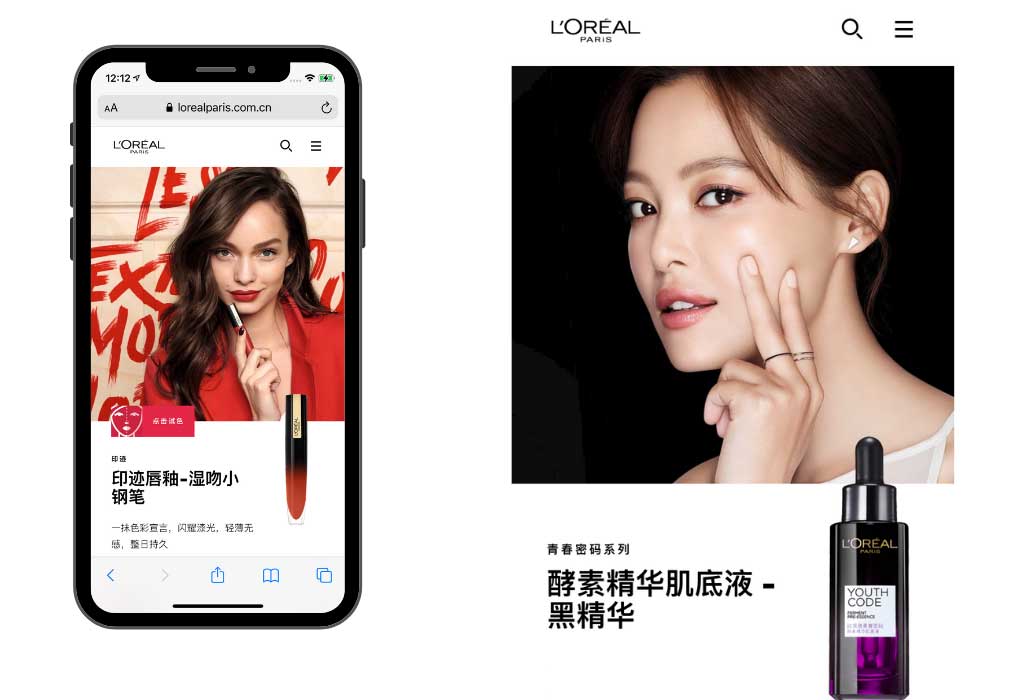
L’Oréal in China: Still the Benchmark in 2026
L’Oréal has been operating in China since 1997. Nearly three decades later, it remains the single most studied foreign beauty brand in the country, and for good reason. The Chinese cosmetics market reached 542 billion RMB in 2025, and L’Oréal holds a top-three position in nearly every category it plays in. No other foreign beauty company has executed localization at this scale. If you want to understand how to sell beauty products in China, start here.
L’Oréal’s Market Position in China: 2026 Data
L’Oréal China operates across 25 brands, two manufacturing plants (Yichang and Suzhou), one research and innovation center in Pudong, and five distribution centers across the country. The Chinese market is now L’Oréal’s second-largest globally, behind only the United States.
In 2025, L’Oréal Group reported that the Asia Pacific zone grew by 6.2%, driven largely by China’s recovery in premium skincare and the continued growth of men’s grooming. Lancôme, Kérastase, and La Roche-Posay are the three strongest performers in the current cycle.
The competitive set has changed significantly. Domestic brands now account for over 35% of the mass market share. Players like Proya, Florasis (花西子), and Winona have moved from niche to mainstream. L’Oréal’s answer has been to accelerate its premium positioning and double down on digital channels rather than compete on price.
The Acquisition Strategy That Built the Foundation
L’Oréal’s entry into China was not built on advertising alone. It was built on smart acquisitions.
The purchase of Yue-Sai in 2004 gave L’Oréal a brand with genuine Chinese identity. Yue-Sai Kan had built that brand for Asian women, specifically for the Chinese consumer. L’Oréal bought the equity, then reformulated the product line with Ganoderma mushroom extracts, a plant with deep roots in traditional Chinese medicine. The 2007 Vital Essential launch showed Chinese consumers that L’Oréal was not simply translating a French product. It was building something local.
The Mininurse acquisition followed a similar logic: buy an established local name, integrate it into the group’s distribution and R&D infrastructure, and grow it with L’Oréal’s global marketing resources. This playbook still works in 2026. Several foreign brands have since copied it, though few have executed it as cleanly.
Digital Strategy: From Weibo to Douyin and XHS in 2026
The original article noted that L’Oréal was slow to adopt Weibo. That gap has been closed, and then some. Today, L’Oréal China runs one of the most active multi-platform digital operations of any foreign beauty brand in the country.
On Xiaohongshu (Little Red Book), L’Oréal’s brands collectively publish hundreds of posts per month. La Roche-Posay has built a particularly strong presence by targeting the “skincare anxiety” segment: users worried about sensitive skin, acne, and pollution damage. The brand connects dermatological credibility with the UGC review culture that defines XHS. It works.
On Douyin, L’Oréal uses a combination of paid livestream slots and KOL partnerships to drive direct-to-consumer sales. During the 618 festival in 2025, Lancôme ran a 12-hour Douyin livestream that generated over 80 million RMB in single-session GMV. This is not a side channel. Douyin is now L’Oréal China’s highest-growth revenue platform.
WeChat remains critical for CRM and repurchase. L’Oréal uses WeChat Mini Programs to run loyalty programs, skin diagnostics, and personalized product recommendations. The data collected through WeChat feeds back into product development at the Shanghai R&D center.
KOL and Celebrity Strategy: More Segmented Than Ever
In 2018, L’Oréal Paris signed Wang Yuan from TFBoys, and the brand sold 13.93 million RMB in products in one month driven by fan purchases. That model still exists, but it has matured significantly.
L’Oréal now runs three tiers of influencer partnerships simultaneously. Top-tier celebrities anchor brand awareness campaigns. Mid-tier KOLs (100k-1M followers) handle category education and product tutorials. Micro-KOLs and regular users generate the review content that Chinese consumers actually trust before purchasing.
In 2025, L’Oréal signed actor Xiao Zhan as ambassador for L’Oréal Men Expert, directly targeting the growing male grooming segment. The campaign reached over 600 million impressions in the first week. At the same time, La Roche-Posay partnered with dermatologists and medical KOLs on XHS, a completely different content register, because the target audience responds to clinical authority rather than celebrity.
The lesson: one celebrity, one channel is not a China strategy. Segmentation by platform, by audience, and by product category is how L’Oréal manages its scale.
Targeting Gen Z and the Male Consumer
The Chinese cosmetics market in 2026 is not the same demographic story as ten years ago. Two shifts define it.
First, Gen Z (born 1997-2012) is now the core purchasing cohort for makeup. These consumers grew up with Douyin and XHS. They do not respond to TV advertising. They trust peer reviews, viral tutorials, and limited-edition drops. L’Oréal Paris responded with the “Color Ramp” sub-line targeted explicitly at this group, with packaging and shades developed in China for Chinese consumers.
Second, male grooming is growing at double the rate of the overall market. The “guochao” (国潮) trend has made personal care more socially acceptable for young Chinese men. L’Oréal Men Expert, which had been a secondary priority for years, is now one of the fastest-growing SKUs in the L’Oréal portfolio in China.
5 Current Trends in Chinese Cosmetics That L’Oréal Is Betting On
- Skinification of makeup: Chinese consumers want makeup that also treats skin. Products with SPF, hyaluronic acid, and niacinamide are outperforming traditional color cosmetics.
- Ingredient transparency: Post-2023 regulations require full ingredient disclosure. Brands that lead with clinical claims and clear ingredient lists win on XHS and with Gen Z.
- Domestic brand pressure: Proya and Florasis are not going away. Foreign brands that do not localize deeply will continue to lose mass-market share.
- Livestream commerce as primary channel: In 2025, over 40% of beauty purchases in China were made via livestream. This number will not go down.
- Sustainability signaling: Chinese Gen Z consumers increasingly expect environmental commitments. L’Oréal’s “L’Oréal for the Future” program has been adapted for the Chinese market with local factory emission targets and refillable packaging pilots in Shanghai.
Olivier Verot’s View
I have worked with foreign beauty brands entering China for over ten years. L’Oréal is the case study I return to most often, not because it is the most exciting story, but because it is the most honest one about what China entry actually requires.
L’Oréal did not succeed because it had good products. It succeeded because it spent money on research in China, built local teams with real authority, acquired local brands instead of dismissing them, and accepted that the Chinese consumer is not a variation of the European consumer. Most foreign brands I meet in 2026 still have not accepted this. They adapt their packaging color and call it localization.
The platform shift from Weibo to Douyin to XHS happened fast. L’Oréal moved with it because it had the budget and the teams in place. Smaller brands cannot rely on that. But the underlying logic is the same: go where the consumer is, produce content in the format she prefers, and build trust before you ask for the purchase. This works for a 10-million-euro brand and for a 100-million-euro brand. The scale is different. The logic is not.
One thing I will say plainly: the brands that are struggling in China right now are almost always the ones that treated digital as an afterthought. You cannot run a China strategy from Paris or New York and expect results. The market moves too fast and the platforms are too different.
4 Mistakes Foreign Beauty Brands Make in China
- Treating XHS as an Instagram substitute. Xiaohongshu is a search engine as much as it is a social platform. If your brand has no presence there, Chinese consumers searching your product name will find your competitors’ reviews instead of your content. This is a distribution problem, not a social media problem.
- Signing one celebrity and stopping. A single top-tier ambassador gives you awareness for a quarter. Without a structured KOL program below that level, you will not convert awareness into sales. L’Oréal runs hundreds of KOL relationships simultaneously. You do not need hundreds, but you need more than one.
- Ignoring Douyin livestream commerce. Many European and American brands still consider livestream selling “not on-brand.” The Chinese consumer does not care. She buys beauty products on Douyin. If you are not there, you are invisible to the fastest-growing purchase channel in the market.
- Using global formulas without adaptation. What sells in France does not automatically sell in China. Skin types differ, humidity differs, and consumer concerns differ. L’Oréal built an R&D center in Shanghai specifically to solve this. You do not need a full R&D center, but you do need to test your products with Chinese consumers before scaling.
5 Questions About L’Oréal and Beauty Brands in China from Chinese Consumers
Q: 欧莱雅在中国卖的产品和欧洲一样吗?(Are L’Oréal products sold in China the same as in Europe?)
A: No. L’Oréal China develops specific formulas for the local market. Several SKUs, including products in the Yue-Sai and La Roche-Posay lines, are exclusive to China and use ingredients selected for Asian skin types and climate conditions.
Q: 欧莱雅的护肤品在小红书上的评价可信吗?(Are L’Oréal skincare reviews on Xiaohongshu trustworthy?)
A: Some are, some are not. L’Oréal partners with both paid KOLs and independent dermatology accounts. Look for posts that disclose the partnership (#广告 or #合作). User reviews with no brand affiliation are generally more reliable for ingredient reactions and texture assessments.
Q: 外国美容品牌和国产品牌有什么区别?(What is the difference between foreign beauty brands and domestic brands?)
A: Foreign brands like L’Oréal tend to lead on R&D heritage, clinical testing, and global brand recognition. Domestic brands like Proya and Winona are stronger on price-to-performance ratio and often faster to adapt to local ingredient trends. Neither is universally better. It depends on what you are treating.
Q: 欧莱雅男士系列在中国受欢迎吗?(Is L’Oréal Men Expert popular in China?)
A: Growing fast. Men’s skincare is one of the highest-growth categories in China right now. L’Oréal Men Expert benefited from the Xiao Zhan campaign in 2025 and now holds a top-five position in the male mass-market skincare segment on Tmall.
Q: 在中国买欧莱雅产品,哪个平台最可靠?(Which platform is most reliable for buying L’Oréal products in China?)
A: Tmall flagship store and JD flagship store are the safest options for authenticity. Douyin official brand accounts are also verified. Avoid third-party sellers on WeChat mini-programs without clear brand verification.
Sources
Understanding how L’Oréal built its position in China gives you the playbook. Executing it for your brand requires adapting each element to your category, your budget, and your timeline. If you want to know where to start for your specific brand, we can tell you in one conversation. Get a free social media audit for your brand in China


